Quality Living Real Estate - Blog
Fix-and-Flip in Denver: How to Find, Finance, and Profit
A fix-and-flip is one specific play inside a much larger category. Real estate investing involves purchasing, owning, managing, renting, or selling property to generate profit or long-term wealth. What separates a flip from a rental is the exit. You buy a property that needs work, improve it, and sell it, rather than holding it for income. In Denver, that model lives or dies on three things: buying the right property at the right number, financing the purchase and the renovation without strangling your margin, and selling before holding costs eat the gain.
What a Fix-and-Flip Is and How It Differs From a Rental
Direct real estate investments involve owning and managing properties. A flipper owns the asset, directs the renovation, and controls the sale. The return comes largely from appreciation realized at the sale, not from monthly income along the way.
Rentals work in the opposite direction. They can provide immediate cash flow from rental income, plus long-term appreciation that is realized when you sell the property. Principal reduction is another piece of a rental's return, and it is only one component. Cash flow, appreciation, tax benefits, and rent growth all contribute to the total.
| Strategy | Primary return source | Time horizon | Owner involvement |
|---|---|---|---|
| Fix-and-flip | Appreciation realized at sale | Short term | High, especially during renovation |
| Long-term rental | Rental income, appreciation, principal reduction | Long term | Ongoing management or a property manager |
| Short-term rental | Rental income with higher turnover | Medium to long term | High, guest turnover and upkeep |
| REITs, mutual funds, ETFs | Pooled property performance | Varies | Low, with no property to manage |
Where a Flip Sits in the Wider Investment Picture
Most investments in real estate fall somewhere between direct and indirect ownership. Direct real estate investments involve owning and managing properties. Indirect real estate involves investing in a pool of money that is used to buy and manage property. REITs, real estate mutual funds, and exchange-traded funds all offer a low-cost, liquid way to invest in real estate. A flip sits at the far end of the direct side: hands-on, concentrated, and illiquid for as long as you own it.
Pooled vehicles reach property types a single flipper never touches, including office buildings, multifamily housing, industrial facilities, retail properties, and specialized real assets such as data centers. Publicly traded REITs, private real estate funds, long-term rentals, and short-term rentals are among the common strategies investors choose. Commercial real estate is the third-largest asset class after equities and fixed income, yet individual investors on average hold a negligible allocation. A flip builds direct exposure, though with far less diversification than a fund provides.
How Flip Returns Actually Add Up
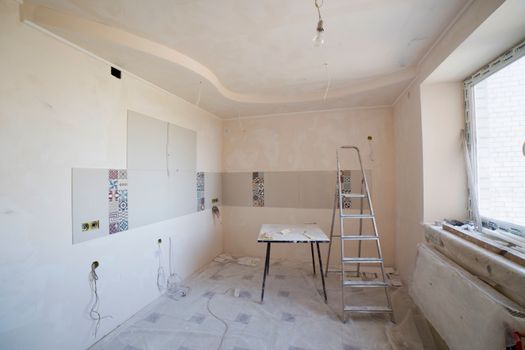
A flip's profit is not one number. It is what the sale brings minus everything you put in: purchase price, renovation cost, financing costs, holding costs, and selling costs. Whatever is left is the return.
Flippers sometimes measure that margin against what a rental of the same property would have produced, which includes cash flow, appreciation, tax benefits, and rent growth. A flip trades away the cash flow and the rent growth in exchange for a faster, one-time gain. Some investors convert a flip into a rental when the market softens rather than selling into a weak pool of buyers.
Real estate investing can offer opportunities for rental income, potential value growth, and possible tax advantages, depending on market conditions. How the tax rules treat a flip depends on your situation and how your activity is classified, so confirm the details with a qualified tax professional before you build them into your numbers.
Finding the Right Property in Denver
- Work the listings consistently. Homes that need work often sit longer than turnkey properties, and the ones drawing fewer competing offers are usually the ones needing the most.
- Ask a local agent about properties that are not listed publicly. Off-market sellers exist, but those introductions come through relationships rather than search filters.
- Consider both single-family and multi-family options. Both appear across the Denver metro inventory, and the math changes with each.
- Judge the property on repair scope first and price second. A cheap house with structural problems rarely stays cheap by the time it is finished.
- Walk the property with the contractor who will do the work. Estimates given from photos tend to fall apart once demolition starts.
Denver pricing and inventory shift constantly, and no two flips carry the same numbers. Verify current market figures with your agent and lender before you write an offer, and treat any older data you find as a starting point only.
Financing the Purchase and the Renovation
Financing structures for a flip vary widely, and the terms come from lenders and private capital sources rather than from a universal formula. Some investors pay cash, some use a loan, and some bring in a partner who contributes capital in exchange for a share of the profit. Each path carries different costs and different levels of risk.
Two questions decide most of the financing conversation. How much of the purchase and renovation can you fund without borrowing, and what happens to your margin if the property sits on the market longer than you planned? Holding costs keep running whether the house sells or not.
Because rates, loan products, and lender requirements change and are not part of the research behind this article, confirm current terms directly with a lender, and confirm the tax treatment with a tax professional before you commit.
Building a Rehab Budget That Holds
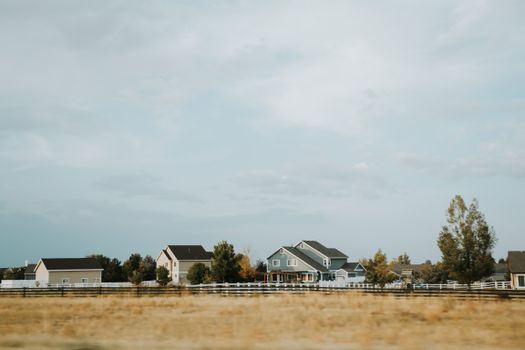
The renovation is where flips go wrong most often. A scope that grows mid-project pushes the sale date and adds cost on both sides of the ledger.
- Define the scope before you make the offer, room by room, with the contractor who will bid the job.
- Price the work from real bids rather than guesses, and ask each contractor what the bid excludes.
- Set aside a contingency for whatever the inspection and demolition reveal.
- Track spending against the budget weekly rather than at the end.
- Confirm permit and inspection requirements with the relevant local authority, since those affect your schedule.
Renovation choices should match the neighborhood and the likely buyer, not your personal taste. Over-improving a house beyond what surrounding sales support is one of the most common ways to lose money on an otherwise solid project.
Mistakes That Sink Denver Flips
- Buying on emotion. A house you love is harder to walk away from when the numbers stop working.
- Underestimating the timeline. Every extra month carries holding costs and market risk.
- Skipping the inspection. Surprises found after closing come out of your margin, not the seller's.
- Financing the entire project with no cushion for overruns.
- Listing at a price the market will not support. Buyers set the sale price, not the budget you spent.
Where a Local Agent Fits In
Quality Living Real Estate is a Denver-based residential agency led by agent Michael Marino, working with clients who buy, sell, and invest across the Denver metro area. For a flip, that means help finding properties worth pursuing, reading the local market when it is time to list, and negotiating on both ends of the transaction.
Buyer representation for fix-and-flip projects is one of the services the agency offers, alongside guidance for first-time buyers, relocation clients, and investors weighing single-family and multi-family property. The same local knowledge that helps a homeowner price a sale helps a flipper decide whether a purchase price leaves room to profit once the work is finished.
Frequently Asked Questions
Is a fix-and-flip a good investment in Denver?
A flip can work well when the purchase price, renovation cost, and sale price leave a real margin after holding and selling costs. It is a concentrated, hands-on strategy rather than a passive one. Because local pricing and inventory change, verify current Denver numbers with a local agent and lender before you commit to a property.
How do I finance a fix-and-flip?
Investors use a mix of cash, lender financing, and partner capital, and the terms come from the lender or investor rather than a standard formula. The right structure depends on how much you can fund yourself and how long you can carry holding costs. Confirm current rates and requirements directly with a lender.
How long does a fix-and-flip take?
Timelines depend on the scope of the renovation, contractor availability, permit and inspection schedules, and how quickly the market absorbs the listing. Longer projects carry more holding cost and more exposure to market shifts. Ask your contractor and lender for realistic estimates specific to your property rather than relying on averages.
Do I need a real estate agent to flip houses?
You are not required to use an agent, but representation helps on both the purchase and the sale. A local agent can surface properties worth reviewing, estimate what the finished home will sell for, and negotiate price and terms. That market read matters most when you are deciding whether a deal leaves enough room to profit.
What should I verify before buying a flip?
Verify the repair scope with a contractor who has walked the property, the permit and inspection requirements with the relevant local authority, and your financing terms with a lender. Confirm how your activity will be taxed with a tax professional. Those checks belong before you remove contingencies, not after closing.
Facebook
Instagram
LinkedIn